Algorithm Optimization vs. Risk Management: The Synergy that Powers Next-Gen Trading Protocols
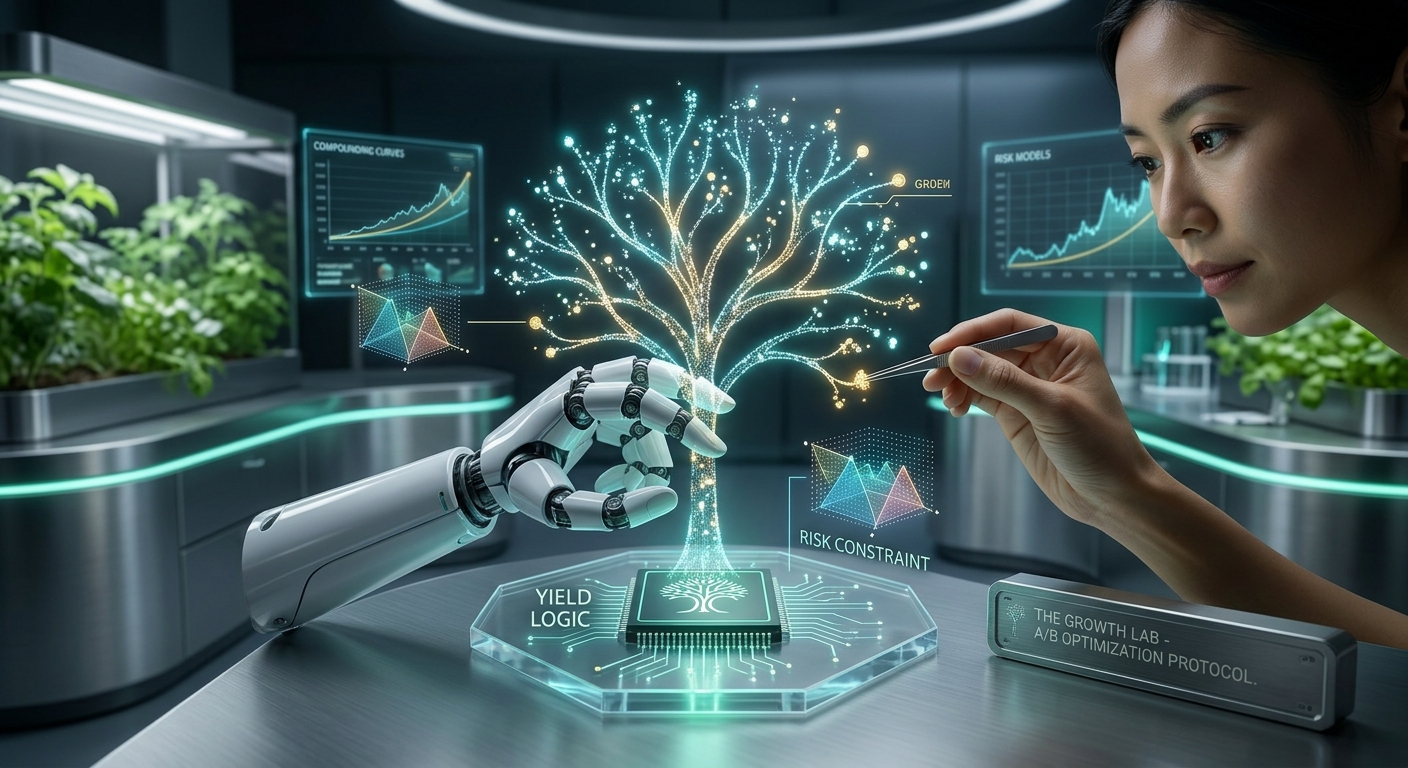
At the core of modern financial innovation—and our own algorithmic trading pools—is a persistent, evolutionary conflict: the symbiotic tension between Algorithm Optimization and Risk Management. One drives performance, while the other guarantees survival. Understanding the delicate balance between these two pillars is crucial for comprehending how modern Fintech platforms generate consistent, sustainable growth in volatile markets.
Algorithm Optimization is the pursuit of alpha—the quest for maximizing performance and identifying statistical inefficiencies. These proprietary protocols are meticulously designed to analyze terabytes of high-frequency data, uncovering microscopic price discrepancies, momentum signals, and order-flow imbalances that are invisible to a human eye. The objective is to refine the logic for faster execution, tighter spreads, and greater capital efficiency. Growth Labs constantly "A/B tests" new strategies, iteratively improving parameters like trade duration, leverage allocation, and asset selection.
However, a hyper-optimized algorithm that ignores systemic risk is like a performance car without brakes. Risk Management is the critical countervailing force. In modern trading protocols, sophisticated risk models run concurrently, calculating VaR (Value at Risk), monitoring maximum drawdowns, and enforcing strict asset-correlation constraints. These models may even preemptively override trading logic when volatility exceeds preset thresholds, protecting the capital base.
True financial innovation is not about choosing one over the other. The magic happens in the synergy. A properly designed automated pool utilizes optimized algorithms to generate high-yield opportunities, but embeds robust, non-negotiable risk constraints directly into the core logic. The growth is not maximized blindly; it is maximized subject to the parameters of the risk model. This combination of statistical precision and disciplined capital preservation is the engine driving consistent, algorithmic wealth generation.